
The ROI of AI: Measuring What Matters
Updated: 16 hours ago

UIB University 365 Institute of Business
Series Business AI Series
Duration 25 minutes
Business Management, Digital Entrepreneurship, Innovation, Finance, Leadership

UNOP Sound (University 365 Neuroscience Oriented Pedagogy)
Take five minutes to prepare your brain. Play the isochronous tone track (40Hz gamma frequency) with your eyes closed. Gamma-frequency tones before a learning session raise attention and make the material easier to absorb.
[Audio player: UNOP Pre-Lecture Isochrone (40Hz, 5 minutes)]
In this Lecture
The Hook: Your Question, Answered
Your company spent $50,000 on AI tools last year. Your CFO wants to know: what did we get for it? If you cannot answer with numbers, next year's AI budget is zero. How do you measure the return on investment of AI in a way that satisfies finance, operations, and strategy?
In this lecture, you will learn how to use AI to tackle this challenge in 15 minutes. The AI handles the data processing and pattern recognition. You handle the judgment and decisions. This is the CI-First approach: human intelligence orchestrates, AI amplifies.

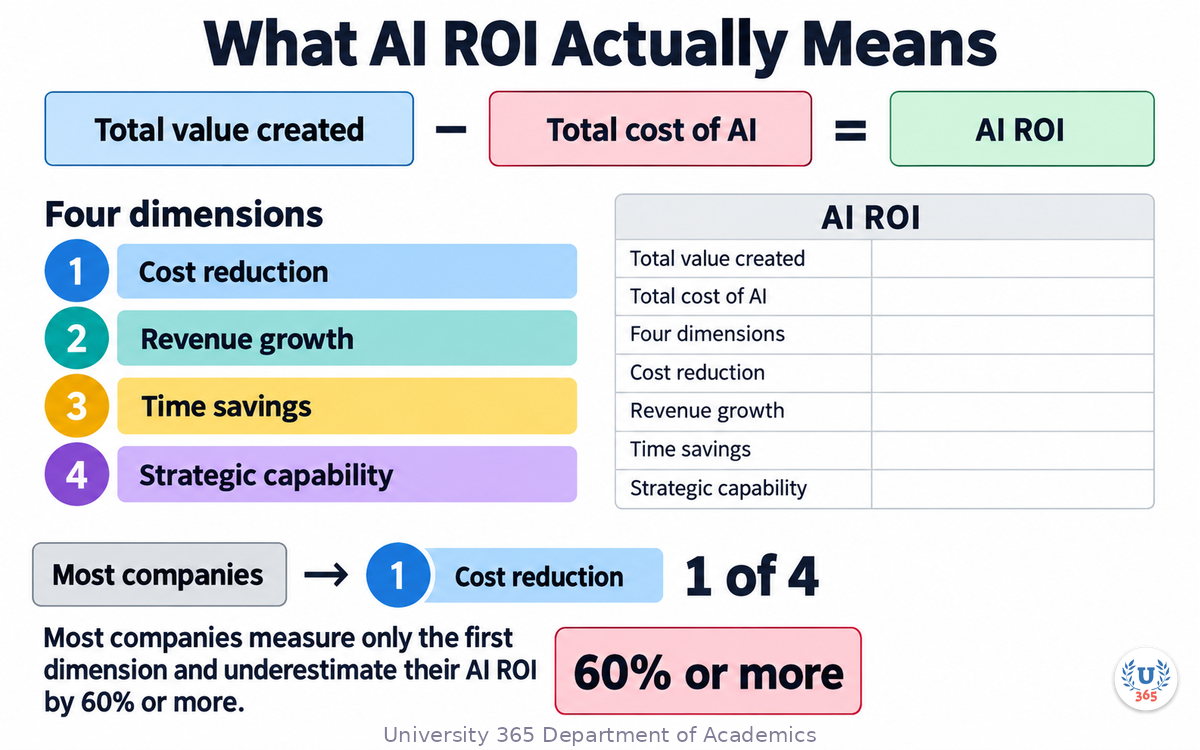
What AI ROI Actually Means
AI ROI is not just cost savings. It is the total value created by AI minus the total cost of AI, measured across four dimensions: cost reduction, revenue growth, time savings, and strategic capability. Most companies measure only the first dimension and underestimate their AI ROI by 60% or more.
Step 1: Measure Cost Reduction
The easiest AI ROI component to measure. How much money did AI save by automating tasks, reducing errors, or replacing expensive tools? Track: labor cost savings, tool consolidation savings, and error reduction savings.
Step 2: Measure Revenue Growth
AI can increase revenue by improving sales conversion, enabling new products, accelerating time-to-market, and improving customer retention. Track: AI-influenced revenue, conversion rate improvements, and retention improvements.
Step 3: Measure Time Savings
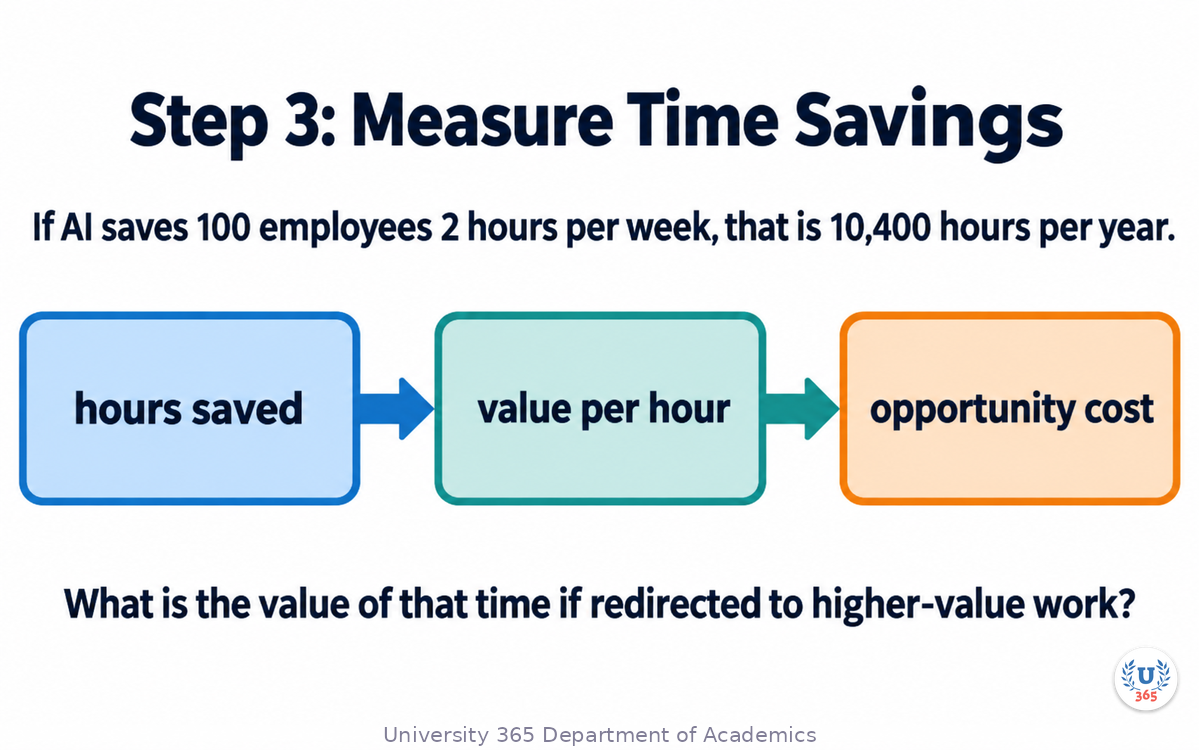
Time savings are the most undermeasured AI ROI component. If AI saves 100 employees 2 hours per week, that is 10,400 hours per year. What is the value of that time if redirected to higher-value work? Calculate: hours saved, value per hour, and opportunity cost.
Step 4: Measure Strategic Capability
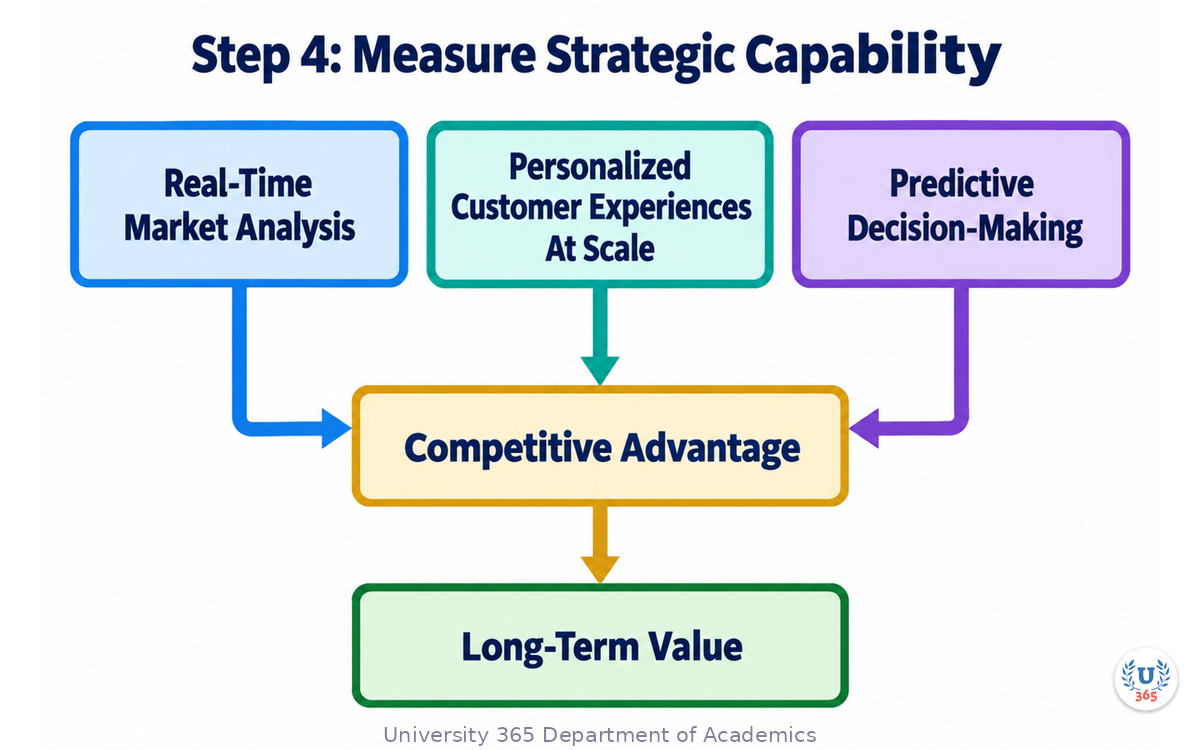
The hardest to measure but often the most valuable. AI enables capabilities that were previously impossible: real-time market analysis, personalized customer experiences at scale, and predictive decision-making. These create competitive advantage that translates to long-term value.
Step 5: Build the ROI Dashboard
Combine all four dimensions into a single ROI dashboard that updates quarterly. Present it to leadership in terms they care about: total ROI percentage, payback period, and strategic value created. Make the invisible visible.
The ROI Baseline: Measure Before You Buy
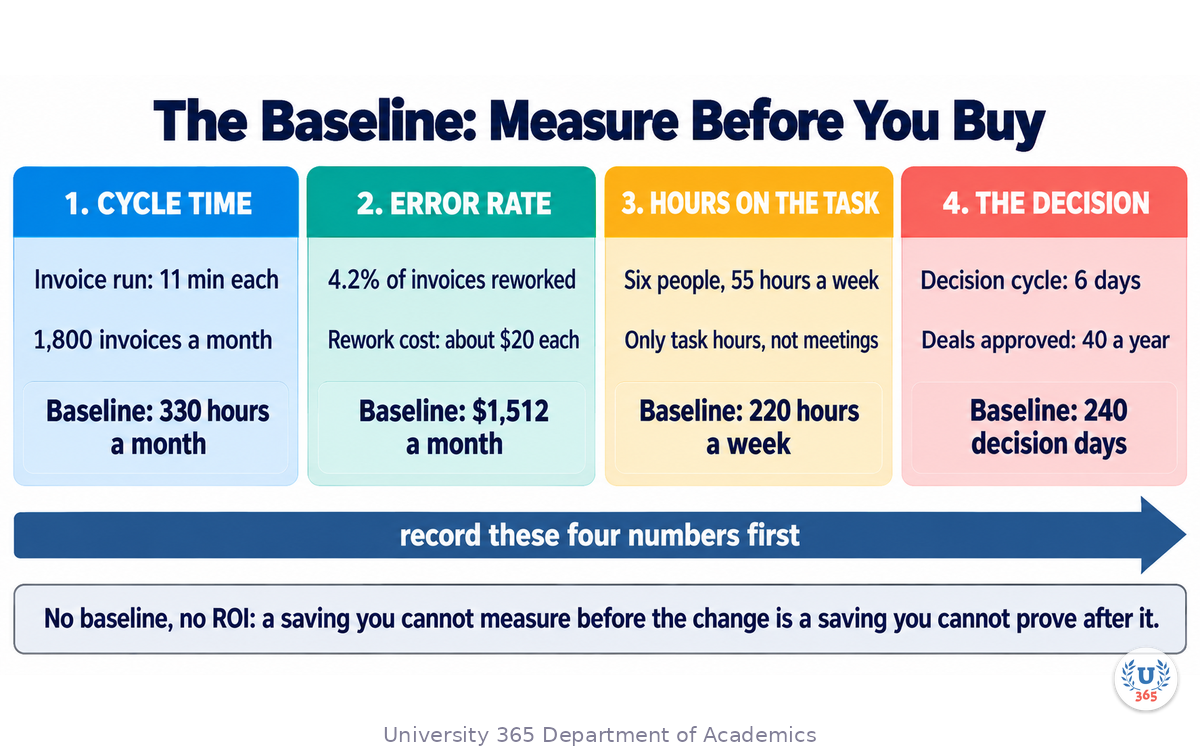
Most teams measure AI ROI after the purchase, from whatever number happens to be lying around. That is why the number is always arguable. You cannot prove a saving you never measured before the change.
The baseline is four measurements taken in the week before you sign anything. They cost you about two hours to collect, and they are the difference between a claim and a finding.
1. Cycle time on the task you are automating
Pick the single task you intend to change, not the department. Count how long one unit takes, end to end, including the waiting between steps. An invoice run is a unit. A candidate screen is a unit. A monthly close is a unit.
The worked example in this lecture uses a billing team that closes 1,800 invoices a month at 11 minutes each. That is 330 hours a month, or about two full-time people doing nothing but invoice work.
2. The error and rework rate
Errors are the cost nobody puts in the business case and everybody pays. Count the share of units that come back for a second pass, and the cost of that second pass. If 4.2 percent of 1,800 invoices are reworked at roughly $20 each, you are spending about $1,512 a month on rework. That number is invisible on the profit and loss statement and obvious the moment you count it.
3. Hours actually spent on the task
Ask people to log only the task hours for one week, not their whole diary. Six people at about 55 hours a week between them is 220 task hours. Do not include meetings, and do not include the time they spend helping other people. Task hours are what AI can compress.
4. The decision you are trying to speed up
Many AI investments are sold as faster decisions rather than cheaper work. If that is your case, measure the decision. How many days from request to answer, and how many such decisions a year. A team that approves 40 deals a year at six days each spends 240 decision days waiting.
Write the four numbers down, date them, and keep them where you will find them in twelve months. A baseline with no date is not a baseline, because the business it describes will have moved.
Cycle time per unit, before the change
Error and rework rate, before the change
Task hours per week, before the change
Decision days per year, before the change
If you cannot collect a baseline because the process is new, say so plainly in the business case. A stated absence of baseline is honest and still usable. An invented baseline is the fastest way to lose a finance director permanently.
Baselines also decide how long you should wait before judging the investment. A process that runs monthly cannot be judged in three weeks. Set the review point to cover at least three full cycles of the task, or one full quarter for a decision process.
The Full Cost Side: What AI Really Costs
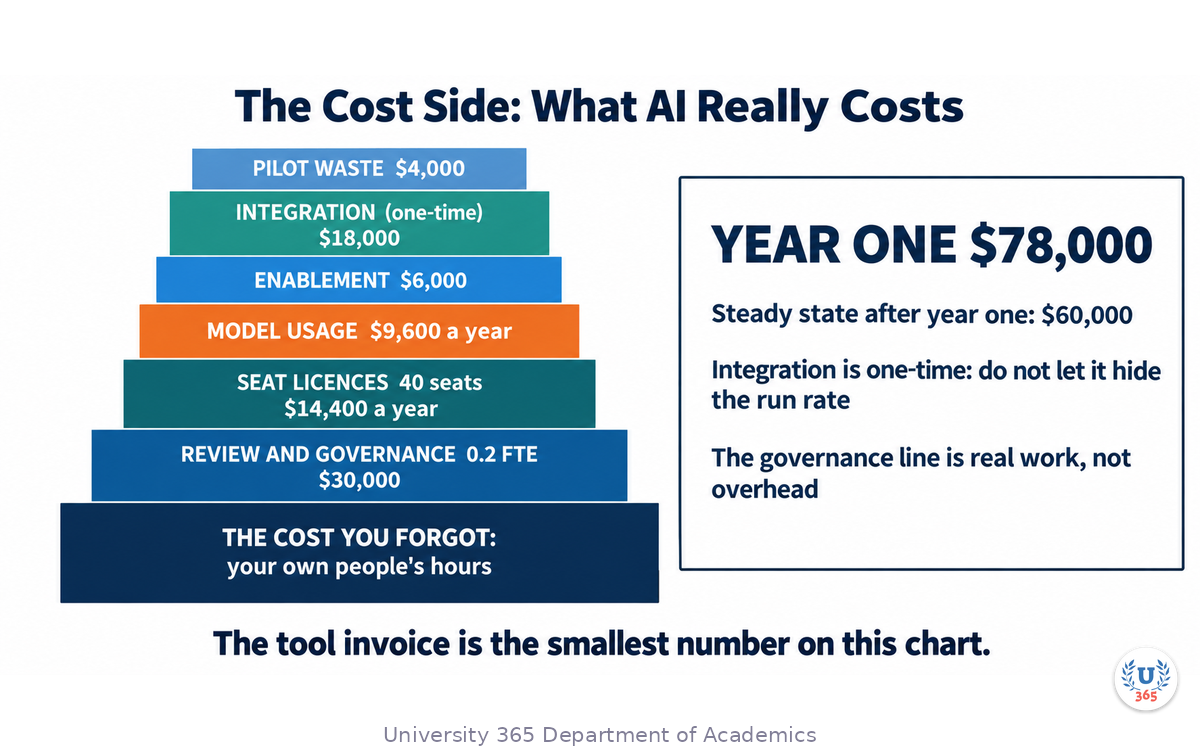
The tool invoice is the smallest number on the cost side, and it is the only one most teams count. Six cost lines belong in an honest ledger.
Seat licences
Count seats the way you will actually pay for them. Forty seats at $30 a seat per month is $14,400 a year whether or not forty people use them. Licence waste is the most common quiet cost of an AI programme: teams buy a hundred seats and ninety are used once.
Model usage
Usage-based model calls sit on top of seats and scale with success. A team that automates more will pay more. Budget $9,600 a year for a mid-sized operational workload and treat any surge as a signal to review, not as a surprise.
Integration, and why it is a one-time line
Connecting the system to your own data is where the real money goes. $18,000 for a first integration is a normal figure. It is a one-time cost, and that matters twice: it inflates year one and it should not be present in your steady-state run rate. Confusing the two is how a project looks unprofitable in year one and then mysteriously profitable in year two, with nobody able to explain the change.
Enablement
Training is not a launch event. Six thousand dollars covers a first enablement programme for a forty-person team. Budget a smaller recurring amount every year after, because staff turn over and tools change.
Review and governance
This is the line teams omit and then discover. Somebody has to review model output, maintain the prompts, fix the failures and document the decisions. For a forty-person team, 0.2 of a full-time equivalent at a $150,000 loaded cost is $30,000 a year. That is real work performed by a real person, and hiding it inside an existing job title does not make it free.
The cost nobody counts: your own hours
Integration projects consume internal time. Track those hours even if you do not charge them to the project, because they compete with other work. A programme that is cheap in cash and expensive in senior attention is not cheap.
Cost line | Basis | Year one | Steady state |
Seat licences | 40 seats at $30 per month | $14,400 | $14,400 |
Model usage | Metered calls | $9,600 | $9,600 |
Integration | One-time build | $18,000 | not recurring |
Enablement | First programme | $6,000 | $6,000 |
Review and governance | 0.2 FTE at $150,000 | $30,000 | $30,000 |
Total | $78,000 | $60,000 |
Read the table twice. The first time it says year one costs $78,000. The second time it says the run rate is $60,000, and the gap between them is a one-time build. Both numbers are true and they answer different questions: the finance director wants the run rate, the board wants the year-one commitment.
There is also an opportunity line that belongs beside the cost, not inside it. Every hour a senior person spends maintaining an AI workflow is an hour not spent on the work only they can do. Name that trade openly rather than netting it off, so the reader can see what you gave up.
The Benefit Side: Four Kinds of Money
The benefit side has four kinds of money in it, and they are not equally reliable. Sort them before you add them.
Hard savings: costs that stop
This is the strongest money because it appears in a bank account. Cancelled tools, consolidated vendors, avoided rework that you were paying for in temporary staff. In the worked example, retiring a duplicate $12,000 tool and consolidating a $10,800 vendor contract gives $22,800 of hard savings. Nobody argues with a cancelled subscription.
Be strict about what counts. A tool that was going to be cancelled anyway is not an AI saving. A vendor contract you renegotiated for unrelated reasons is not an AI saving. Hard savings require a document that shows the payment ending.
Time savings: the most under-measured line, and the easiest to over-claim
If AI removes two hours a week from each of forty people, that is 4,160 hours a year. The temptation is to multiply all 4,160 hours by a salary rate and book the result. Do not. Most recovered time goes back into the same work, more of it, or into email.
The honest method is to agree a redirect share before you begin. In the worked example the team agrees that 15 percent of recovered time, 624 hours, will be redirected to work that was previously not done at all, valued at $95 an hour. That gives $59,280. The other 85 percent is a quality-of-life gain, real for the people involved and not a line in a financial case. Say that out loud and the number survives scrutiny.
Revenue benefit: attribute a share, not the whole lift
AI rarely closes a deal on its own. It improves the information the seller walks in with. So measure the lift and claim only part of it.
In the worked example the team wins 22 percent of proposals without AI and 26 percent with it. At 40 proposals a year and a $22,750 gross profit per win, the baseline gross profit is about $200,200 and the improved figure is about $354,900. The lift is $154,700. Attributing 40 percent of that lift to AI gives $61,880, with a defensible range of $30,940 to $92,820 depending on how much of the improvement you are willing to credit to the tool.
The 40 percent is a judgement, and you must state it as one. A finance director will accept a stated attribution rate and argue with an unstated one.
Strategic capability: name it, do not price it
Some benefits are real and not yet quantifiable: the ability to answer a market question in an afternoon, to personalise at a scale that was previously impossible, to keep a capability in-house instead of buying it as a service. Put these in the narrative and leave them out of the arithmetic. Mixing an unpriced benefit into a total ROI percentage weakens every priced number beside it.
Benefit kind | Evidence required | Counted in ROI? |
Cost stopped | A payment that ends, or a rework invoice that stops arriving | Yes, in full |
Time redirected | An agreed redirect share and an hourly value | Yes, the share only |
Revenue lift | A measured lift, an attribution rate and a gross margin | Yes, the attributed part |
Strategic capability | A named capability and an owner | No, narrative only |
One more discipline: add a second, independent benefit before you conclude anything. In the worked example, one additional large deal won on improved proposal quality contributes $22,750 of gross profit that has nothing to do with the conversion-rate maths. When a total rests on one mechanism, the reader has only one thing to disbelieve, and they usually will.
The Arithmetic: From Ledger to ROI
With a cost ledger and a sorted benefit list, the calculation itself takes one line. The discipline is in what you are allowed to divide by.
Cost, year one
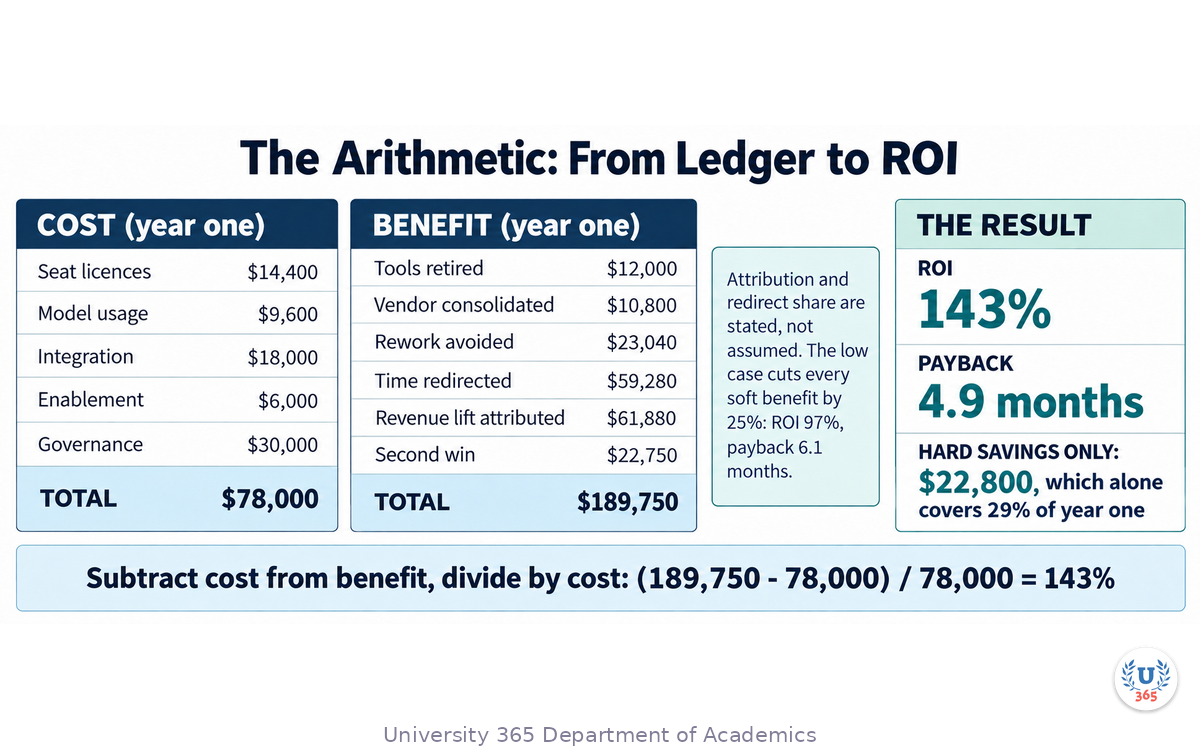
Add every cost line you are actually committing to in the first twelve months. In the worked example that is $78,000: $14,400 of seats, $9,600 of usage, $18,000 of integration, $6,000 of enablement and $30,000 of review and governance.
Benefit, year one
Add only what you can point at: $12,000 of retired tools, $10,800 of consolidated vendor spend, $23,040 of avoided rework, $59,280 of redirected time, $61,880 of attributed revenue lift and $22,750 from one additional large deal. The total is $189,750.
The two figures leadership actually uses
Return is benefit minus cost, divided by cost: $189,750 minus $78,000 is $111,750, divided by $78,000 gives about 143 percent. That is the headline.
Payback is how long the benefit takes to cover the cost: $78,000 divided by the monthly benefit of about $15,813 gives about 4.9 months. That is the figure that unlocks the next budget, because it says when the risk ends.
The number that answers the sceptic
Hard savings alone are $22,800, and they cover 29 percent of year one with no soft claim at all. Lead with that when the room is hostile. The soft lines then become upside rather than the argument.
The sensitivity that makes the case credible
Present the low case beside the base case. Cut every soft benefit by 25 percent: rework, redirected time and attributed revenue all fall, and the total benefit drops to $153,700. Return falls to about 97 percent and payback stretches to 6.1 months. Cut the soft benefits by 40 percent and return is about 69 percent with a 7.1 month payback.
A case that still returns 69 percent when you deliberately weaken its softest assumptions is a case that survives a bad meeting. A case that collapses when questioned was never a case.
Three arithmetic traps
First, do not annualise a pilot. Three weeks of results is not a run rate, because usage climbs and the task mix changes. Second, do not net the one-time integration cost out of year one and then present a payback figure that assumes it never happened. Third, do not add percentages from different bases: a 30 percent time reduction on one workflow and a 10 percent cost reduction overall are not additive.
Return = (benefit minus cost) divided by cost
Payback = cost divided by monthly benefit
State the redirect share and the attribution rate as assumptions
Show the low case: cut the soft benefits by 25 percent
Build the Dashboard Leaders Actually Read
A single ROI percentage is a conclusion, not a management tool. A dashboard is what lets a leader steer.
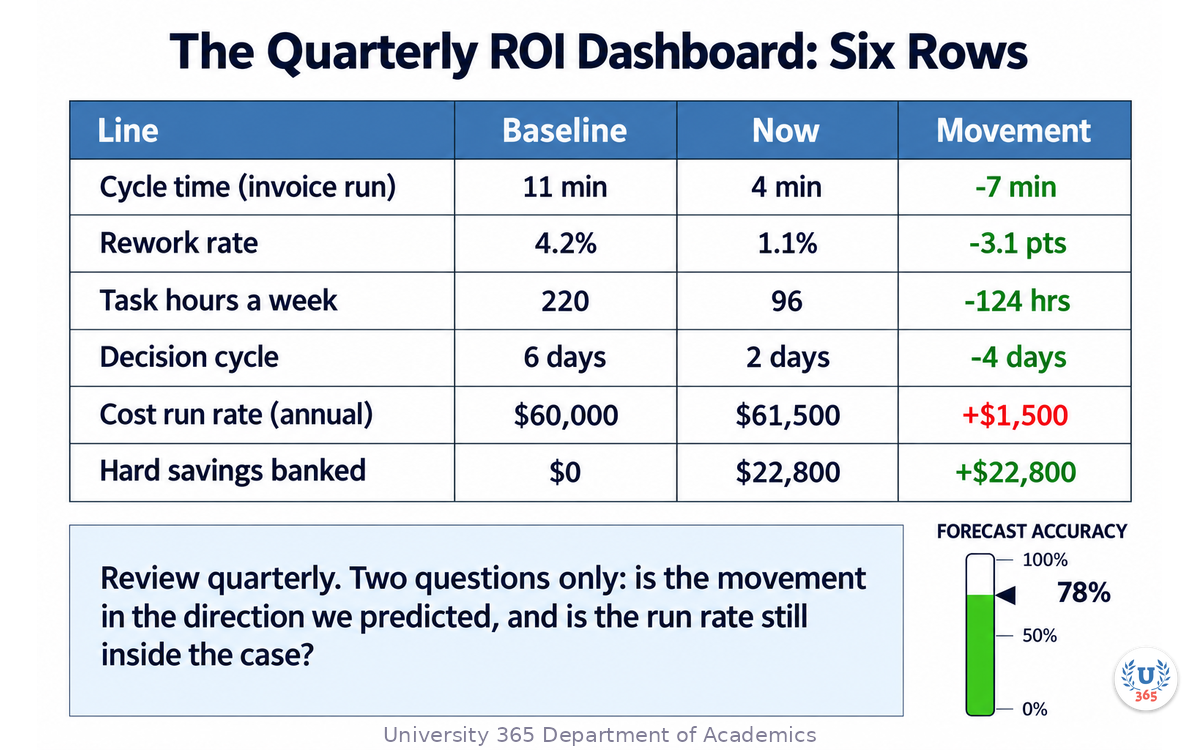
Six rows are enough. Each carries the metric, the baseline you recorded, the current reading and the movement. Nothing else belongs on the first page.
Line | Baseline | Now | Movement |
Cycle time per invoice | 11 min | 4 min | 7 min faster |
Rework rate | 4.2 percent | 1.1 percent | 3.1 points better |
Task hours a week | 220 | 96 | 124 hours released |
Decision cycle | 6 days | 2 days | 4 days faster |
Cost run rate | $60,000 a year | $61,500 a year | $1,500 higher |
Hard savings banked | $0 | $22,800 | $22,800 |
Report the cost row even when it moves the wrong way
In the worked example the run rate rose by $1,500, because usage grew as more of the team automated more of the work. That is a good outcome reported honestly, not a failure concealed. A dashboard whose cost row can only ever fall is a dashboard nobody trusts.
Two questions per quarter, no more
Is the movement in the direction we predicted, and is the run rate still inside the case? If the answer to the first is no, the forecast was wrong and you should say by how much. If the answer to the second is no, the investment needs a decision, not another quarter of watching.
Add one forward-looking row
Every dashboard should carry one number that is not a result yet. Forecast accuracy is the usual choice: of the last ten forecasts your team produced with AI in the loop, how many landed inside five percent? A dashboard that only looks backwards cannot warn you.
Keep the audience in mind
Operations wants cycle time and error rate. Finance wants the run rate and payback. The executive team wants the strategic capability and the risk. Put the same six rows in front of all three, and let each reader take the row they own. Rebuilding the dashboard per audience is how the numbers drift apart.
Publish it on a fixed date. A quarterly dashboard that arrives when it is ready is a report. One that arrives in the first week of every quarter is a control.
Case Study: Twelve Months in a Finance Team
This is a composite worked example drawn from the arithmetic in this lecture. The figures are illustrations, not a benchmark, and they are here so you can see the method run end to end.
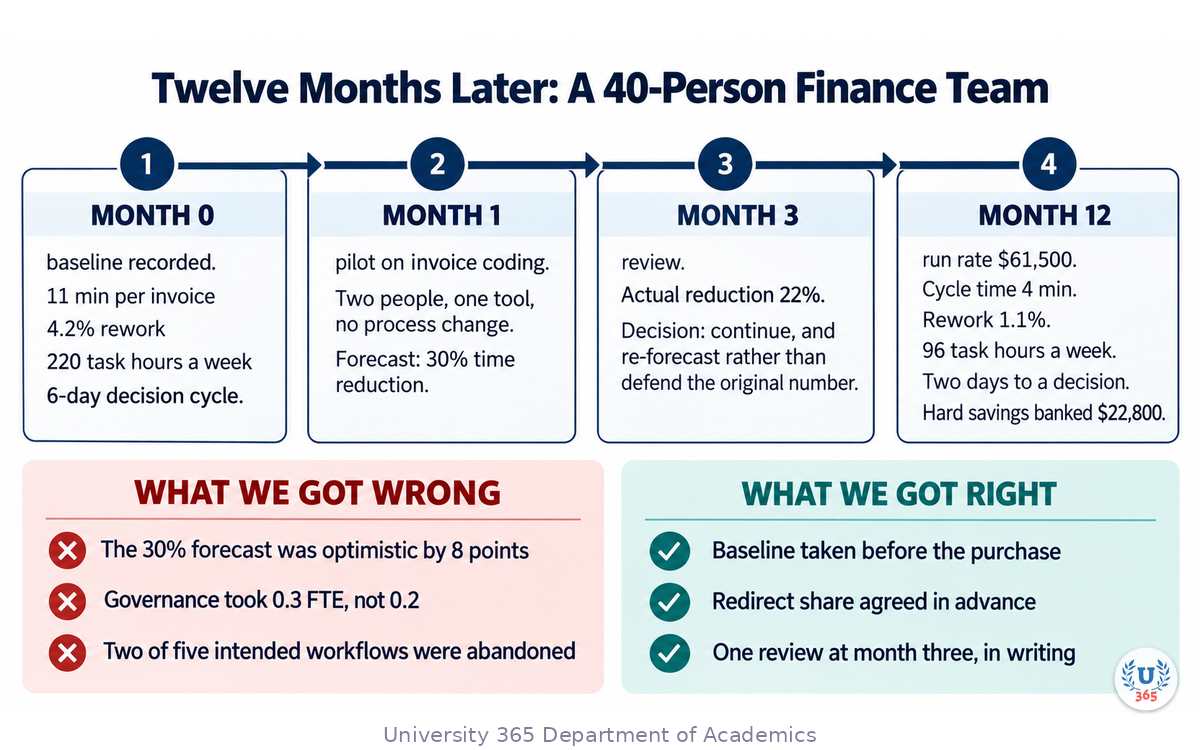
Month zero: the baseline
A forty-person finance function records four numbers before buying anything. Invoices take 11 minutes each across 1,800 a month. Rework runs at 4.2 percent of invoices at about $20 each. Task hours across six people total 220 a week. Deals are approved in six days, forty times a year.
Month one: a deliberately narrow pilot
Two people, one tool, one task: invoice coding. No process redesign, no new system. The team forecasts a 30 percent reduction in time on task, and writes the forecast down before starting, which is the only way it can later be judged.
Month three: the review that made the rest possible
The actual reduction is 22 percent, eight points short of the forecast. The team reports the miss and re-forecasts instead of defending the original number. Governance consumption is measured at 0.3 of a full-time equivalent rather than the 0.2 assumed, and the cost ledger is corrected. Two of the five planned workflows are cancelled because the data to support them is not clean enough.
This review is the reason the programme survives. A team that corrects its own numbers publicly earns the right to propose the next phase.
Month twelve: the result
Invoice cycle time is four minutes. Rework is 1.1 percent. Task hours are 96 a week. Decisions take two days. The run rate is $61,500 against a $60,000 plan, and the increase is explained: usage grew because adoption grew. Hard savings banked are $22,800. Against a year-one cost of $78,000, the case returns roughly 143 percent in the base reading, and it still returns about 69 percent with every soft benefit weakened by 40 percent.
What transfers to your own case
Decision | What happened | What to copy |
Baseline timing | Taken before the purchase | Record four numbers, date them |
Pilot scope | Two people, one task | Narrow enough to fail cheaply |
Forecast | Written down, then missed by 8 points | Report the miss, re-forecast |
Governance cost | 0.3 FTE, not 0.2 | Measure it, do not assume it |
Workflow count | Five planned, three delivered | Plan for partial delivery |
The pattern worth copying is not the 143 percent. It is that every assumption was written down before it could be tested, and every miss was reported in the next review. That is what makes an ROI figure survive a year of questions.
Where the Return Lands: ROI by Business Model
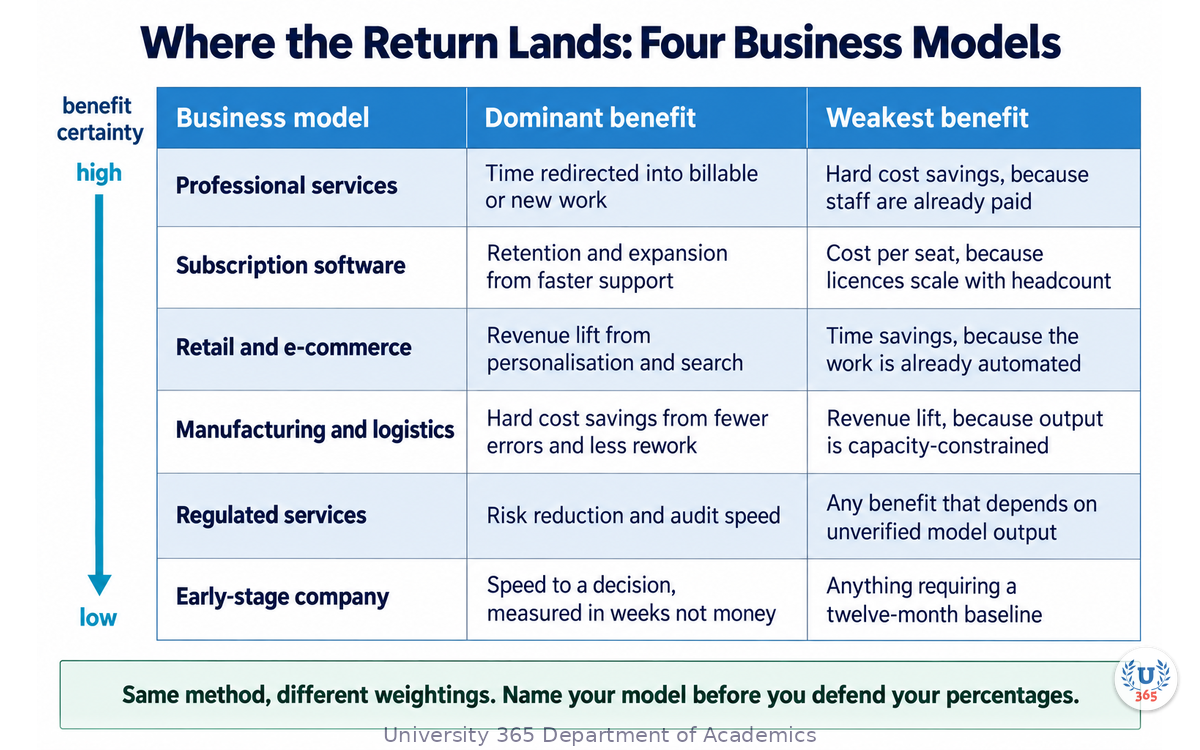
The method does not change with your business model. The weightings do. A team that defends the wrong benefit for its model spends a year measuring the number that will never move.
Professional services
Your dominant benefit is time redirected into billable or previously unsold work, and your weakest benefit is hard cost savings, because your people are already paid whether or not AI helps them. Sell the case to your partners as capacity, not as headcount reduction. A consultancy that promises headcount savings and then redeploys the same people has broken its own case.
Subscription software
Retention and expansion move faster than anything else in this model. Faster support, better onboarding and quicker answers to a prospective customer all show up in churn and in seat expansion, and both are already measured. The weak line is cost per seat, because licences scale with headcount and headcount is the thing you are trying to grow.
Retail and e-commerce
Revenue lift from search, recommendation and personalisation dominates. Time savings are weak because the operational work is largely automated already. Measure conversion by segment and average order value, not hours.
Manufacturing and logistics
Hard cost savings dominate, because errors and rework have a direct price and your output is usually constrained by capacity rather than demand. Revenue lift is weak here: producing slightly better forecasts does not sell one more unit if the line is already full.
Regulated services
Risk reduction and audit speed are the real benefits, and they are hard to price. Any benefit that depends on unverified model output is weak by construction, because the regulator will not accept it. Measure the reduction in remediation hours and the shortening of the audit cycle, and put them in the narrative.
Early-stage company
Speed is the benefit, measured in weeks rather than money. You have no twelve-month baseline and no stable process, so most of the standard arithmetic will not hold. State the decision you are trying to reach faster and by when, and judge the investment on that.
Business model | Dominant benefit | Weakest benefit |
Professional services | Time redirected to billable or new work | Hard cost savings |
Subscription software | Retention and expansion | Cost per seat |
Retail and e-commerce | Revenue lift from personalisation | Time savings |
Manufacturing and logistics | Fewer errors and less rework | Revenue lift |
Regulated services | Risk reduction and audit speed | Unverified output |
Early-stage company | Speed to a decision | Anything needing a 12-month baseline |
Name your model at the top of the business case. It tells the reader which two rows you will hold yourself to and which four you are deliberately not claiming.
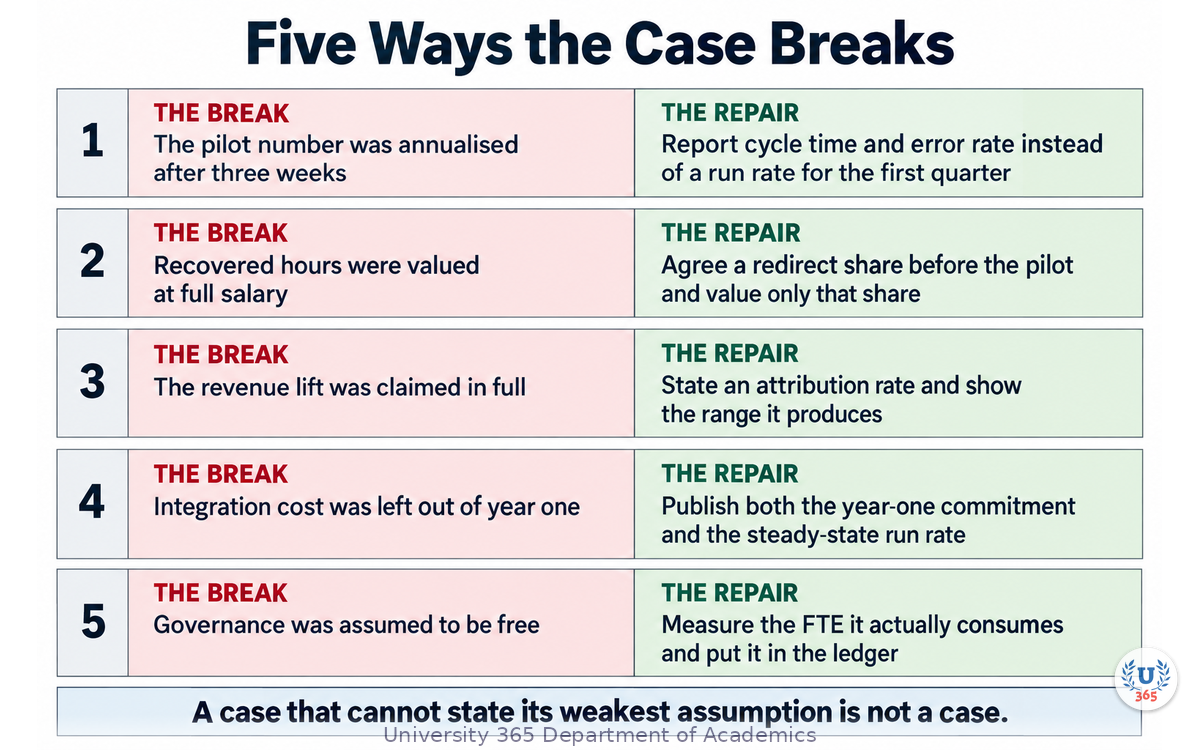
Five Ways an AI ROI Case Breaks
Most AI business cases do not fail because the technology failed. They fail because one of five assumptions was never examined.
1. Annualising a pilot
Three weeks of a two-person pilot is not a run rate. Usage climbs, the task mix changes, and the people who volunteered are not the average. Report cycle time and error rate for the first quarter, and state a run rate only once you have three full cycles of data.
2. Valuing every recovered hour at a full salary
This is the single most common overstatement. Recovered time that goes back into the same work has no financial value, however good it feels. Agree a redirect share before the pilot, value only that share, and name the work it is redirected into. If nobody can name the work, the share is zero.
3. Claiming the whole revenue lift
A conversion rate that improves while an AI tool is in use is not proof that the tool caused the improvement. Claim an attribution rate, show the range it produces, and let the reader choose where in that range they sit. A stated 40 percent survives the meeting. An unstated 100 percent does not.
4. Leaving integration out of year one
One-time build costs are real money in the year they are spent. A case that omits them shows a short payback and then a surprise. Publish both figures: the year-one commitment and the steady-state run rate. The finance director needs the second and the board needs the first.
5. Treating governance as free
Somebody reviews the output, maintains the prompts, handles the failures and documents the decisions. That is a fraction of a job, and fractions of jobs cost money. Measure the fraction after the first quarter rather than assuming it, because it is almost always larger than the plan.
The repair pattern that covers all five
Write every assumption down before the pilot starts, with the date and the person who owns it. Then review them in writing at a fixed point. The month-three review in the case study is the mechanism, not an extra: it is what converted five fragile assumptions into one corrected case that survived to month twelve.
The break | The repair |
Pilot annualised after three weeks | Report cycle time and error rate for a quarter first |
Recovered hours valued at full salary | Agree a redirect share before the pilot |
Revenue lift claimed in full | State an attribution rate and show the range |
Integration left out of year one | Publish year-one commitment and steady-state run rate |
Governance assumed free | Measure the FTE consumed and ledger it |
Run this list against your own draft before anyone else does. Four of the five breaks are visible on the page to a careful reader, which means they are visible to the person deciding your budget.
Putting It Together: Build Your Case in 90 Minutes
Everything in this lecture fits into a single sitting. Block ninety minutes, work through the five steps below in order, and you will finish with a case a finance director can read without asking you to come back.
Minutes 0 to 20: record the four baseline numbers
One unit of work, its cycle time, its error and rework rate, the task hours per week and the decision days per year. Date the sheet. If a number is unavailable, write the reason beside it rather than leaving a blank, because a blank invites a guess.
Minutes 20 to 45: build the cost ledger
Six lines, with the basis written next to each one: seats, usage, integration, enablement, governance and internal hours. Separate the year-one commitment from the steady-state run rate and label both. If you cannot estimate governance yet, put a range and say it will be measured after the first quarter.
Minutes 45 to 70: sort the benefits and set the two assumptions
Split the benefit list into cost stopped, time redirected and revenue lift, and set the two numbers that decide everything: the redirect share and the attribution rate. Write both down with the name of the person who agreed to them. Then compute the low case, cutting the soft benefits by 25 percent, before you compute the base case.
Minutes 70 to 85: compute return, payback and the hard-savings floor
Return is benefit minus cost divided by cost. Payback is cost divided by the monthly benefit. The hard-savings floor is the part of the benefit that appears in a bank account, and it is the number you lead with when the room is sceptical.
Minutes 85 to 90: write the single paragraph that decides the meeting
Three sentences: what we measured before, what we expect it to become, and how we will know if we were wrong. Put the review date in the paragraph. A case with a stated review date is a plan, and a plan is much harder to refuse than a request.
Step | Output | Time |
1. Baseline | Four dated numbers per unit of work | 20 minutes |
2. Cost ledger | Six lines, year one and steady state separated | 25 minutes |
3. Benefit sort | Three buckets, two stated assumptions | 25 minutes |
4. Arithmetic | Return, payback, hard-savings floor, low case | 15 minutes |
5. The paragraph | What we measured, what we expect, the review date | 5 minutes |
Ninety minutes is the whole method. What takes a quarter is collecting the four numbers, and that work cannot be compressed, because it is the work that makes the result undeniable.
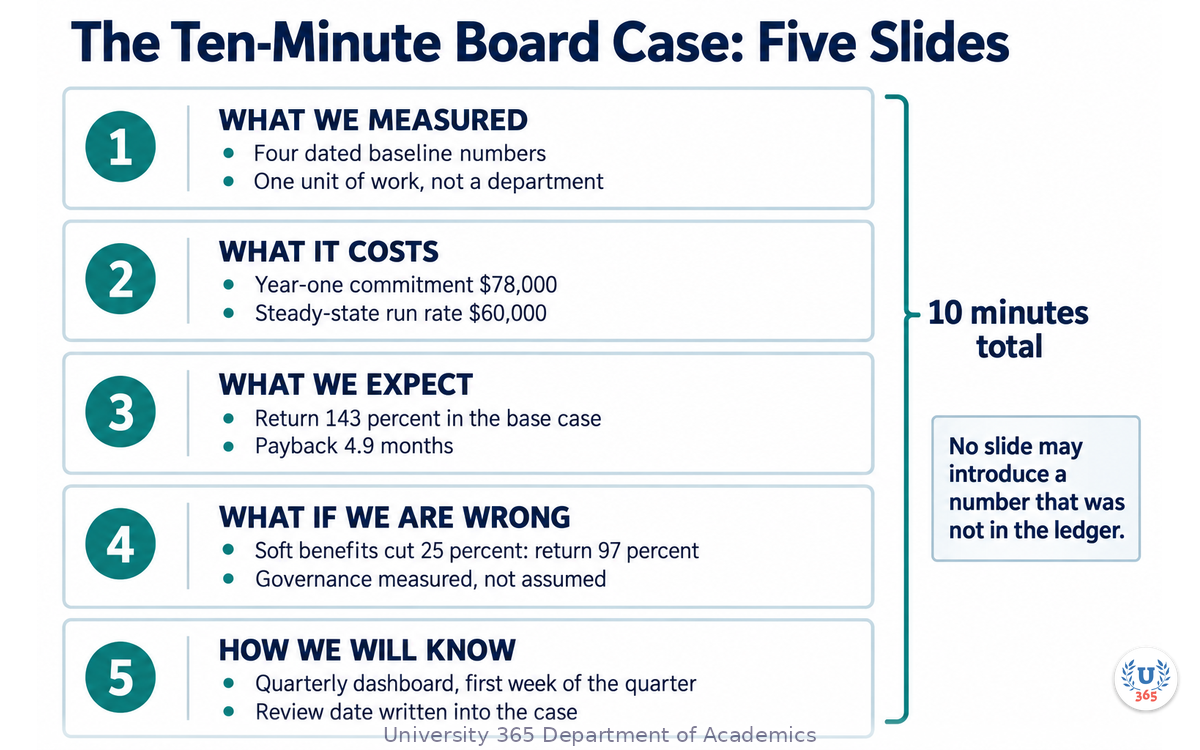
The Ten-Minute Board Case
You will rarely get more than ten minutes to defend an AI investment. The order of the argument matters more than its length.
Slide one: what we measured
Open with the four dated baseline numbers and the one unit of work they describe. This slide does the most work in the room, because it tells the reader that the case is grounded in something they can check. A department-level claim invites a department-level argument. One unit of work is a fact.
Slide two: what it costs
Give both figures. The year-one commitment of $78,000 is what the board is being asked to approve. The steady-state run rate of $60,000 is what the investment looks like once the one-time build is behind it. Presenting only one of the two is the fastest way to lose a finance director, because they will ask for the other one immediately.
Slide three: what we expect
Lead with payback rather than return. Payback of about 4.9 months tells the room when the risk ends, and risk is what a board is actually weighing. Follow with the return, and state the redirect share and the attribution rate on the same slide, in smaller type, so nobody can say later that they were not told.
Slide four: what if we are wrong
This is the slide most presenters omit, and it is the one that closes the decision. Show the low case: cut every soft benefit by 25 percent and the return is still about 97 percent with a 6.1 month payback. A case that survives its own worst assumptions is not an optimistic case, it is a robust one.
Slide five: how we will know
Name the dashboard, the reporting cadence and the review date. In the worked example the review happened at month three and the forecast was missed by eight points, which was reported rather than defended. Say in advance that you will report a miss. It removes the fear that a miss will be concealed.
The two rules for the room
First, no slide may introduce a number that was not in the ledger. The moment a figure appears that nobody can trace, every other figure on the page becomes arguable. Second, answer the cost question before it is asked. A presenter who volunteers the uncomfortable number is treated as the reliable source in the room.
When the room is hostile
Lead with the hard-savings floor. In the worked example, $22,800 of cancelled tools, consolidated vendor spend and avoided rework covers 29 percent of year one with no soft claim at all. It is a smaller number and a much harder one to argue with. Once it is on the table, the soft benefits become upside rather than the argument, and the conversation changes.
Then invite the challenge yourself. Ask which assumption the room considers weakest, and answer it with the sensitivity you already computed. A presenter who offers the first objection keeps control of the second one.
Five slides, ten minutes, in this order
Payback before return, because payback is the risk statement
Lead the hostile room with the hard-savings floor
State the review date and promise to report a miss
Feynman Summary: Explain It Like You Are 12
Imagine you have a problem to solve at work. It usually takes a long time and a lot of effort. Now imagine you have a super-smart robot friend who can do the boring parts in seconds.
That is what AI does for measuring ai: measuring what matters. The robot reads all the information, finds the patterns, and shows you the results. You look at what the robot found and decide what to do.
The robot does not make the final decision. You do. The robot just does the hard work of gathering and organizing information so you can focus on thinking and deciding.
That is the CI-First way: you are the boss, the AI is your helper. Together, you get better results faster.
Mindmap: The Complete Picture
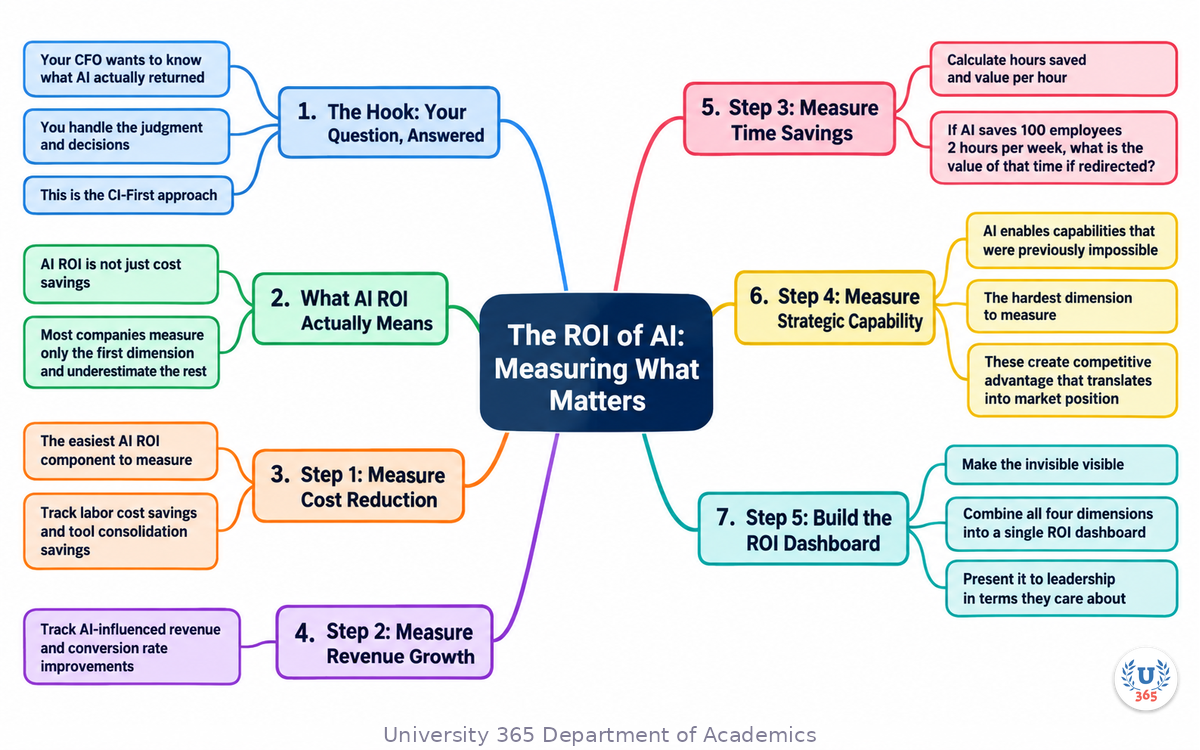
The mindmap shows the complete workflow: defining your objective leads to gathering and preparing data, which feeds into AI analysis and processing, which produces insights and recommendations, which you validate with human judgment before taking action. The CI-First principle wraps the entire process: you start with human-defined goals and end with human-validated decisions.
UNOP Sound (University 365 Neuroscience Oriented Pedagogy)
Take five minutes to consolidate your memory. Play the isochronous tone track (10Hz alpha frequency) with your eyes closed. Alpha-frequency tones after a learning session support consolidation, helping move what you just learned from short-term to long-term memory.
[Audio player: UNOP Post-Lecture Isochrone (10Hz, 5 minutes)]
Practical Exercise: Apply What You Learned
Exercise: 15-Minute Application Sprint
Identify a real scenario: Think of a situation in your work or business where this topic applies.
Define your objective: What specific outcome do you want to achieve in 15 minutes?
Use an AI tool: Open ChatGPT, Claude, or Gemini and apply the framework from this lecture.
Analyze the output: Did AI produce useful results? What needs verification? What needs human judgment?
Make a decision: Based on AI output plus your judgment, what action will you take?
What to Look For
Did AI produce specific, actionable output or generic statements? Generic output means your prompt needs more context.
Did AI invent any data or make unsupported claims? Always verify critical facts against primary sources.
What would you do differently from what AI suggested? The gap between AI output and your judgment is where your value lies.
The CI-First formula is CI = HI + (AI x HI). Your intelligence is the foundation. AI multiplies it. But the final decision is yours.
Applied AI Connection
This exercise demonstrates the CI-First workflow in practice. You defined the objective (human intelligence). AI processed and analyzed (AI amplification). You validated and decided (human intelligence). The speed gain from AI lets you iterate faster and explore more options than you could manually.
Glossary
Term | Definition |
AI ROI | The return on investment of AI initiatives, measured across cost reduction, revenue growth, time savings, and strategic capability. |
Cost Reduction | Money saved by AI through automation, error reduction, and tool consolidation. |
Revenue Growth | Additional revenue generated through AI-enabled improvements in sales, retention, and new capabilities. |
Time Savings | Hours saved by employees through AI automation, valued at the opportunity cost of redirected work. |
Strategic Capability | New abilities that AI enables which were previously impossible, creating competitive advantage. |
Payback Period | The time required for AI benefits to equal the initial investment cost. |
Opportunity Cost | The value of the next best alternative use of time or resources that AI frees up. |
CI-First | Co-Intelligence First: the U365 principle that human intelligence orchestrates and AI amplifies. CI = HI + (AI x HI). |
5M2S | 5 Minutes to Success: the U365 principle of using AI to compress time-intensive tasks into minutes. |
UNOP | University 365 Neuroscience-Oriented Pedagogy: the pedagogical framework behind all U365 lectures. |
ROI Dashboard | A visual report combining all AI value dimensions into a single view for leadership decision-making. |
Value per Hour | The estimated monetary value of an employee's time, used to calculate the financial impact of time savings. |
Quiz: TEST YOUR UNDERSTANDING
1. What are the four dimensions of AI ROI?
A) Cost reduction, revenue growth, time savings, and strategic capability
B) Hardware, software, training, and support
C) Sales, marketing, operations, and HR
D) Revenue, expenses, assets, and liabilities
2. What is the most undermeasured AI ROI component?
A) Time savings, because companies fail to value the redirected hours
B) Cost of AI licenses
C) Server maintenance costs
D) Employee training costs
3. If AI saves 100 employees 2 hours per week, how many hours is that per year?
A) 10,400 hours per year
B) 200 hours per year
C) 5,200 hours per year
D) 1,000 hours per year
4. Why do most companies underestimate their AI ROI?
A) Because they measure only cost reduction and miss revenue, time, and strategic value
B) Because AI ROI is impossible to measure
C) Because their finance teams are incompetent
D) Because AI always loses money
5. What should an AI ROI dashboard include?
A) Total ROI percentage, payback period, and strategic value created, updated quarterly
B) Only the cost of AI tools
C) Only employee satisfaction scores
D) Only the number of AI models deployed
Answers: 1-B, 2-B, 3-B, 4-B, 5-B
Related Resources
U365 INSIDE Publications
Book Essential: Co-Intelligence by Ethan Mollick: The Centaur model and human-AI collaboration
Lecture 1: AI for Market Research: First lecture in the Business AI Series
External Resources
Harvard Business Review: AI in Business: How AI is transforming business operations: hbr.org
McKinsey: The State of AI: Annual report on AI adoption: mckinsey.com
Stanford AI Index: Annual report on AI progress and adoption: aiindex.stanford.edu
Related U365 Lectures (Coming Soon)
Other lectures in the Business AI Series at UIB
Cross-institute lectures on AI applications
U.Copilot for This Lecture
Discuss this lecture with U.Copilot, your AI chat companion trained on this content.
Copy and paste the following prompt into the U.Copilot chat on university-365.com:
You are U.Copilot for Lectures, an AI chat companion specially trained on University 365 lecture content. You are helping a Fellow who just completed the lecture "The ROI of AI: Measuring What Matters" from the Business AI Series at the U365 Institute of Business (UIB). Your role is to help the Fellow deepen their understanding of this topic. You can: - Clarify any concept from the lecture - Provide additional examples and practical applications - Explain how to use specific AI tools for these tasks - Discuss how to verify AI outputs and apply human judgment - Help the Fellow apply the CI-First approach to their own work - Suggest follow-up learning based on the Fellow's industry and interests Always maintain U365's CI-First approach: encourage the Fellow to think critically, verify AI outputs, and maintain human judgment as the orchestrator of AI tools. Use the UP-Context-Engineering Method: provide context-rich, role-aware responses that account for the Fellow's learning level and goals.
Next Steps
Now that you have completed this lecture, here is what to do next:
Try the practical exercise above to apply what you learned to a real scenario
Experiment with different AI tools to see which works best for your specific use case
Explore other lectures in the Business AI Series at UIB
Apply the CI-First approach to your daily work: ask "how can AI help?" before starting any task
Join a UIB program if you want structured learning in business management and digital entrepreneurship: visit university-365.com/tuition
The companies that succeed in the AI age are not the ones with the most AI tools. They are the ones whose people know how to direct AI effectively and apply judgment to its outputs. This lecture gave you the framework. Now practice it.
IMPORTANT NOTICE
This lecture is published by University 365 as part of its INSIDE Publications Hub. The content is free to read for all visitors. Lectures in this series may be part of a structured academic program leading to a Micro-Credential for your Career (MCC). To enroll in an academic program, visit university-365.com/tuition.
This content is for educational purposes. While we strive for accuracy, AI is a fast-moving field. Verify current tool capabilities and market data against primary sources for professional applications.
Copyright University 365, Inc. All rights reserved. This content is protected under University 365's copyright policies. For permissions or inquiries, contact uda@university-365.com.
Published by the Department of Academics, University 365.
Lecture delivered by the University 365 Institute of Business (UIB).
Denise Cromwell, Dean of Business, UIB
Signed for the academic year 2026.



Comments